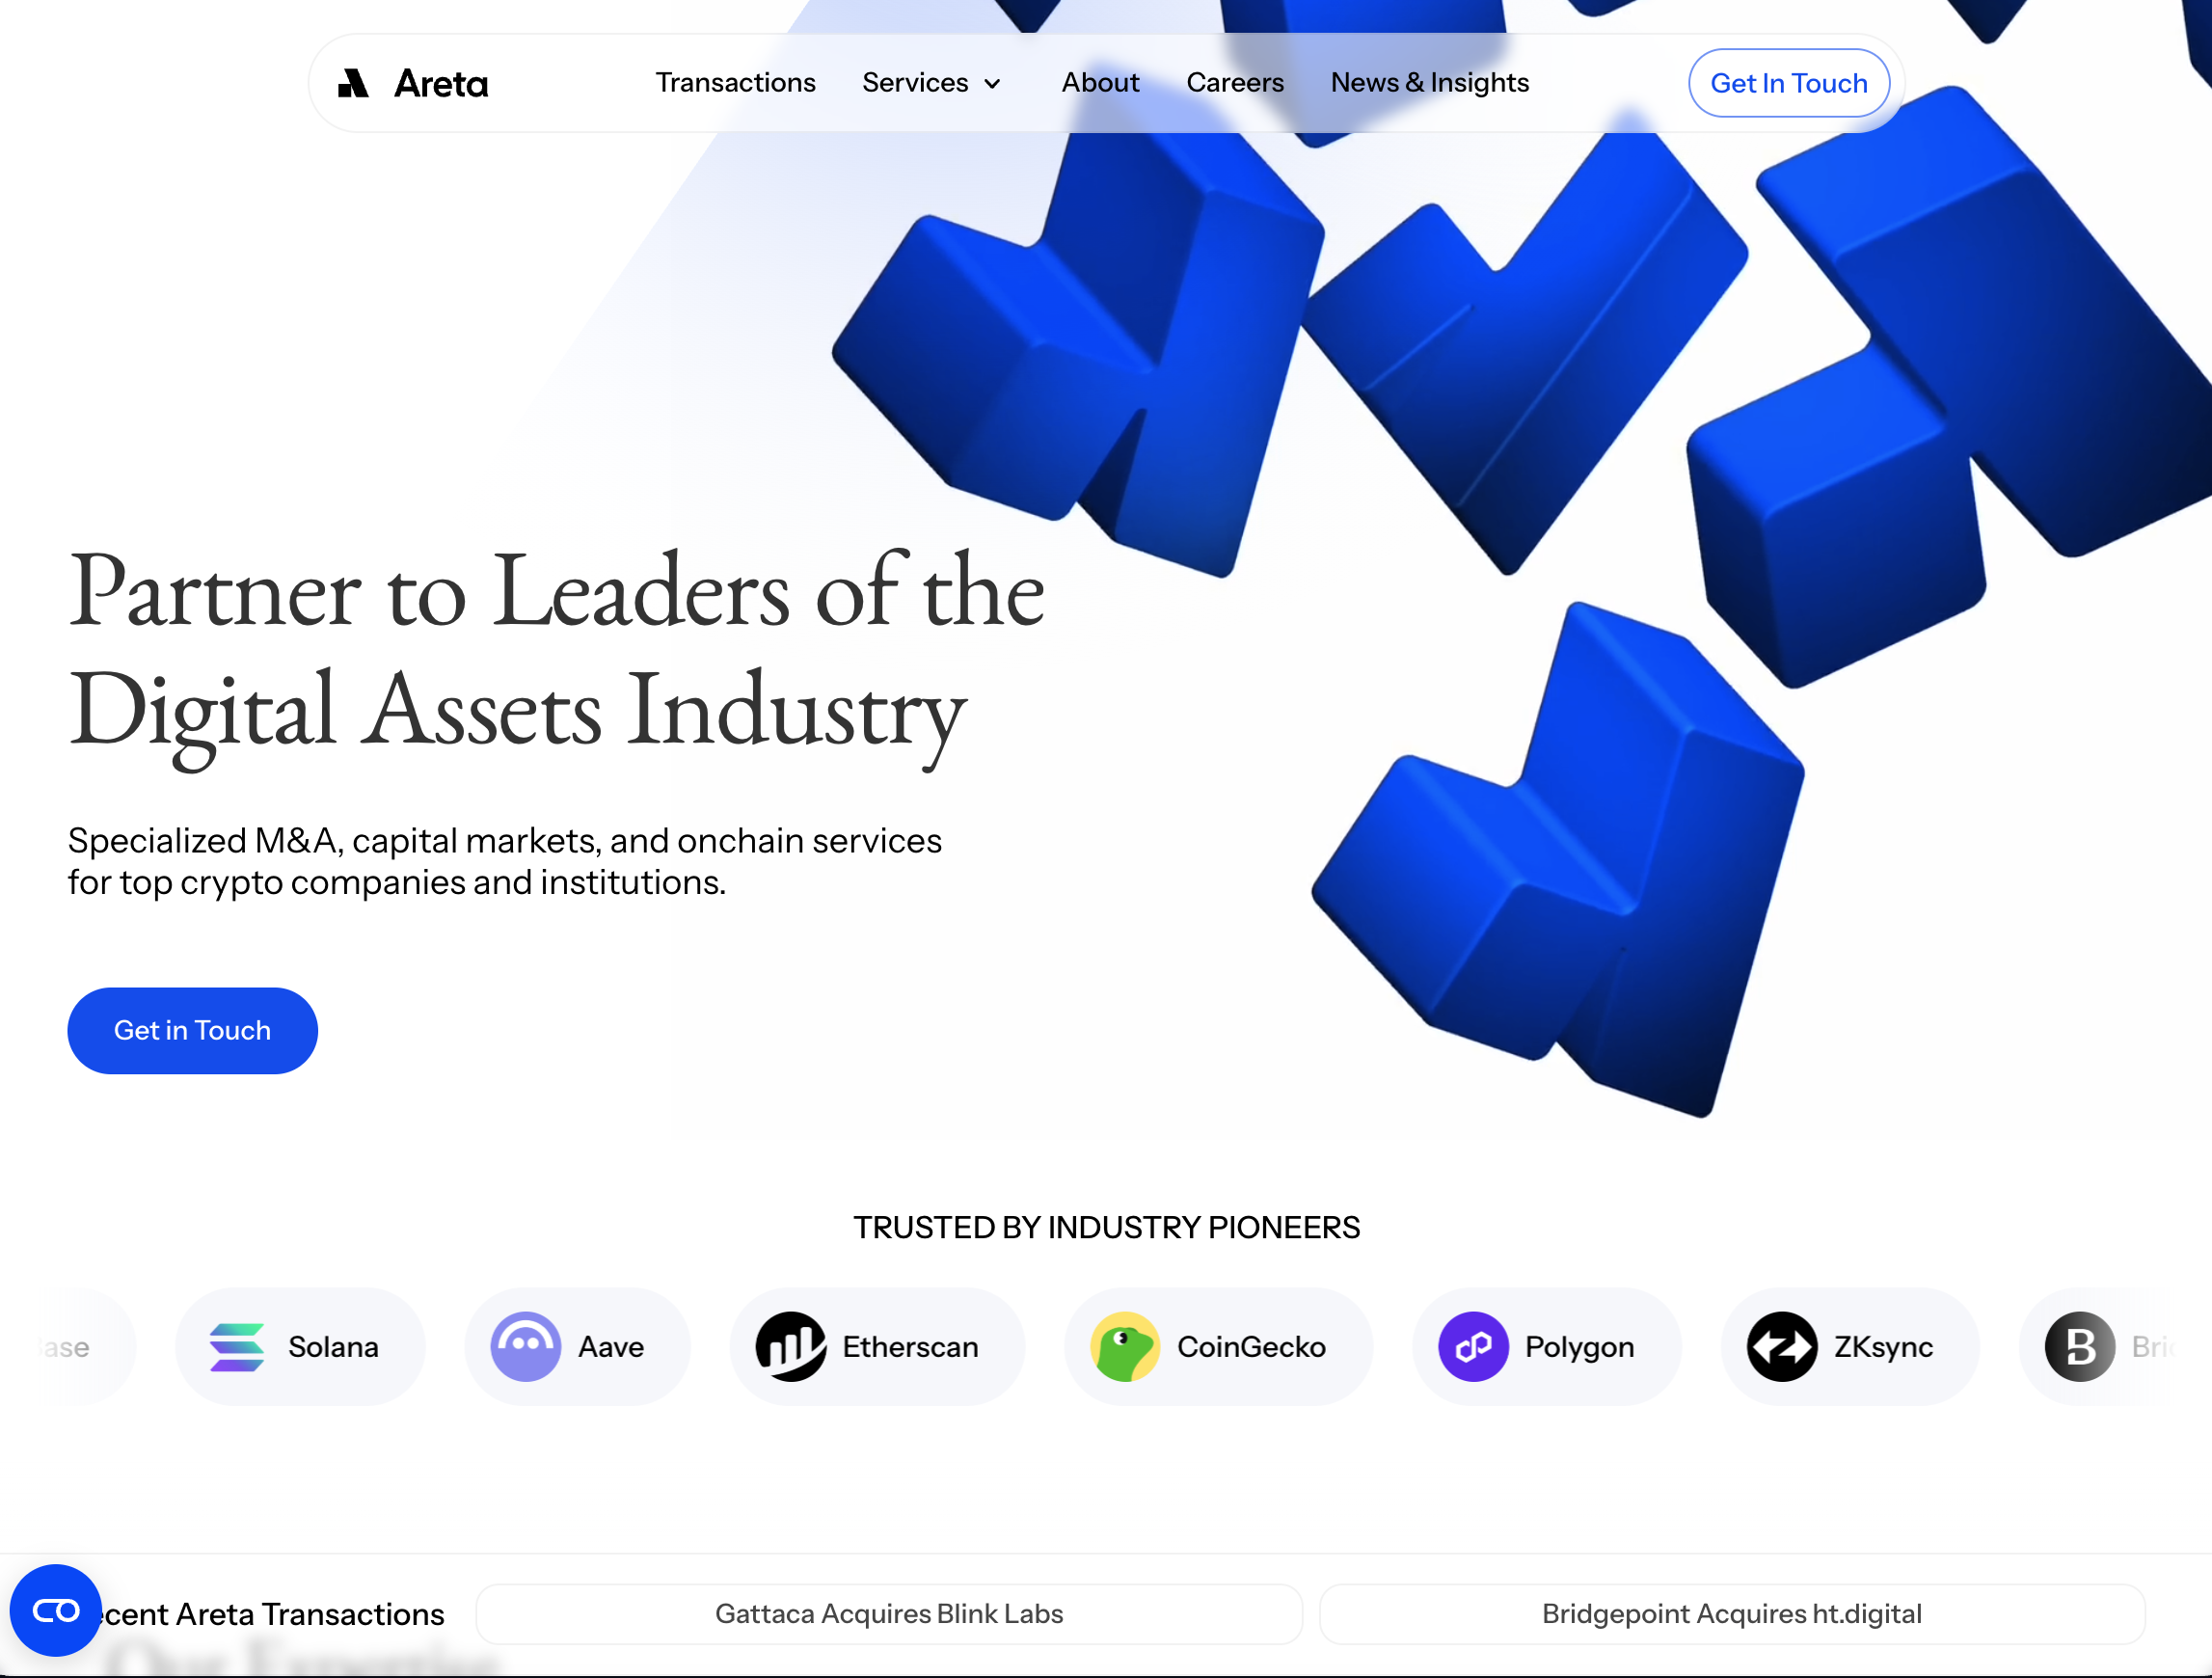
Areta.io is not presented as a retail cryptocurrency investment website. Its current pages describe an advisory business working on mergers, acquisitions, capital raising and strategic assignments for digital-asset companies. That distinction matters: a visitor looking for a trading account, promised yield or an investment withdrawal process would be evaluating the wrong type of service. Our November 3, 2026 review identified a named German operating company and independent records consistent with its disclosed address. We found no substantiated basis to describe this domain as fraudulent. That finding is limited to the public evidence examined, not an endorsement of a transaction or advisory engagement.
What areta.io actually offers
The official website lists three main practice areas. Mergers and acquisitions involve advising buyers and sellers; capital-markets work includes private fundraising, secondary transactions, token launches and liquidity-related assignments; onchain services concern protocol strategy, governance and delegation. These are predominantly business-to-business activities. The site does not invite ordinary readers to open a deposit account or advertise a fixed personal investment return.
This is an important counterpoint to the way an unfamiliar crypto-related URL can appear on a complaint or watch list. Inclusion in such a list says nothing by itself about whether the business is a broker, custodian or adviser, or whether any complaint refers to the correct company. Areta’s service description requires a different due-diligence approach from one used for consumer exchanges.
Company identity and registration evidence
Areta’s German imprint identifies Areta GmbH, gives Kienberger Allee 4, 12529 Schönefeld, Germany, and names managing directors Jan-Philip Grabs, Karl-Martin Ahrend and Bernard Schmid. The legal-entity identifier record for Areta GmbH independently records the same company name and Schönefeld address, describes the entity as active and links it to German registration HRB 18768. An LEI corroborates a legal identity; it is not a financial-services licence.
A German register-data provider also identifies HRB 18768 at the Cottbus court. Its company-purpose summary describes strategic advice in finance and blockchain and specifically excludes activity requiring certain permissions. This helps establish what the registered company says it does, but does not independently settle whether every real-world mandate requires authorisation in a particular country. Clients should assess the legal nature of their specific proposed engagement.
Track record: useful disclosures, but check deal roles
The firm’s transactions directory presents named advisory assignments, including an announced 2026 Finrate AG sale to The Tie and earlier crypto-infrastructure transactions. These names provide leads clients can check against counterparty announcements and documents. They are more informative than unsupported claims of outstanding performance, although a company-maintained directory cannot independently prove every described role or fee arrangement.
One limitation is that headline figures and prestige statements on a marketing website can be difficult to verify. The live homepage’s animated statistics did not expose reliable totals in the text available for this review, so we have not repeated transaction-volume, staffing or ranking figures as established facts. Likewise, displaying a project’s logo should not automatically be treated as evidence of a present commercial relationship.
Regulatory considerations and investor protections
Neither a company registration nor an LEI gives Areta permission to perform every potentially regulated financial service. Whether a licence is necessary depends on the precise instrument, client, jurisdiction and role. Public-domain searches undertaken for this review did not surface an exact-domain official warning, but this is not equivalent to a comprehensive clearance from all regulators. We did not access a definitive cross-border permission determination or inspect individual client contracts.
Before commissioning capital-raising or transaction work, ask which legal entity will sign the mandate, whether any other group company participates, which laws govern the agreement and how compensation is calculated. Confirm potential success fees, exclusivity periods, conflicts of interest and custody arrangements. An advisory brand should not be mistaken for a regulated deposit taker or a guarantee of funding.
Observed risk and practical conclusion
Within InvestorWatchdog’s seven-flag framework, this initial evidence supports no affirmative flags: identifiable executives, a corroborated business address, no fixed-return retail offer and no documented withdrawal-refusal case connected to the reviewed domain. Several flags are not naturally applicable to a conventional advisory mandate. The provisional zero-point observation therefore means only that the model has not identified its defined red flags; it does not measure the quality of professional advice or contract risk.
Our assessment is that areta.io has a materially more verifiable operating identity than an anonymous crypto deposit platform. A client should still request references, check the exact transaction counterparties and obtain independent legal advice for significant engagements. InvestorWatchdog’s methodology explains why evidence and business-model fit matter more than a domain’s appearance on a screening list.
Frequently asked questions
Does areta.io offer retail crypto investment accounts?
Not on the pages reviewed. Its publicly described services concern institutional advisory, fundraising and onchain strategy, rather than consumer deposits or advertised personal yield.
Can Areta GmbH’s existence be independently checked?
Yes. Its legal name and address correspond to an active LEI record and German company-register information. These records establish identity, not universal regulatory authorisation.
Does a zero-point red-flag result make areta.io risk-free?
No. It means none of the specified scam-watch flags was substantiated in this preliminary review. Contractual, execution and jurisdiction-specific risks still require separate examination.
Conclusion: Our Assessment of areta.io
Areta.io has a publicly identifiable advisory business behind it, and the available evidence does not justify treating it like an anonymous retail investment scheme. The practical risks are more specific: confirm which legal entity will sign your mandate, check relevant professional authorizations where required, and review success fees, exclusivity, conflicts of interest and transaction counterparties before committing.
Have you worked with Areta or discovered a material error in this review? Share a documented account so the evidence can be assessed fairly. For broader comparisons, browse InvestorWatchdog investigations and review our investor-protection resources.
A low observed-red-flag result is not a guarantee of commercial performance.